
Does United States-Based Investor Have Homefield Advantage? U.S. Department Of State Deploys Competition For Control Of Canada's Sherritt International Corporation
/“AD HOC GROUP REPRESENTING MAJORITY OF SHERRITT NOTEHOLDERS DISCLOSES RECAPITALISATION ALTERNATIVE AND CALLS ON BOARD TO ENGAGE
Ad Hoc Group of the 9.25% 2031 Notes of Sherritt International Corporation
bold text added for emphasis
TORONTO, Aug. 7, 2026 /PRNewswire/ -- An ad hoc group of holders representing a majority of the outstanding principal amount of Sherritt International Corporation's 9.25% 2031 Notes (the "Ad Hoc Group") today disclosed key terms of a recapitalisation transaction submitted to Sherritt International Corporation ("Sherritt" or the "Company") on 26 June 2026 by a consortium of strategic and financial investors and called on the Board to engage immediately with all credible alternatives.
The Ad Hoc Group will reject any attempt to present them with a take-it-or-leave-it transaction after outcomes have effectively been predetermined. Meaningful engagement with noteholders must occur before key economic and governance terms are finalised in any transaction requiring noteholder consent.
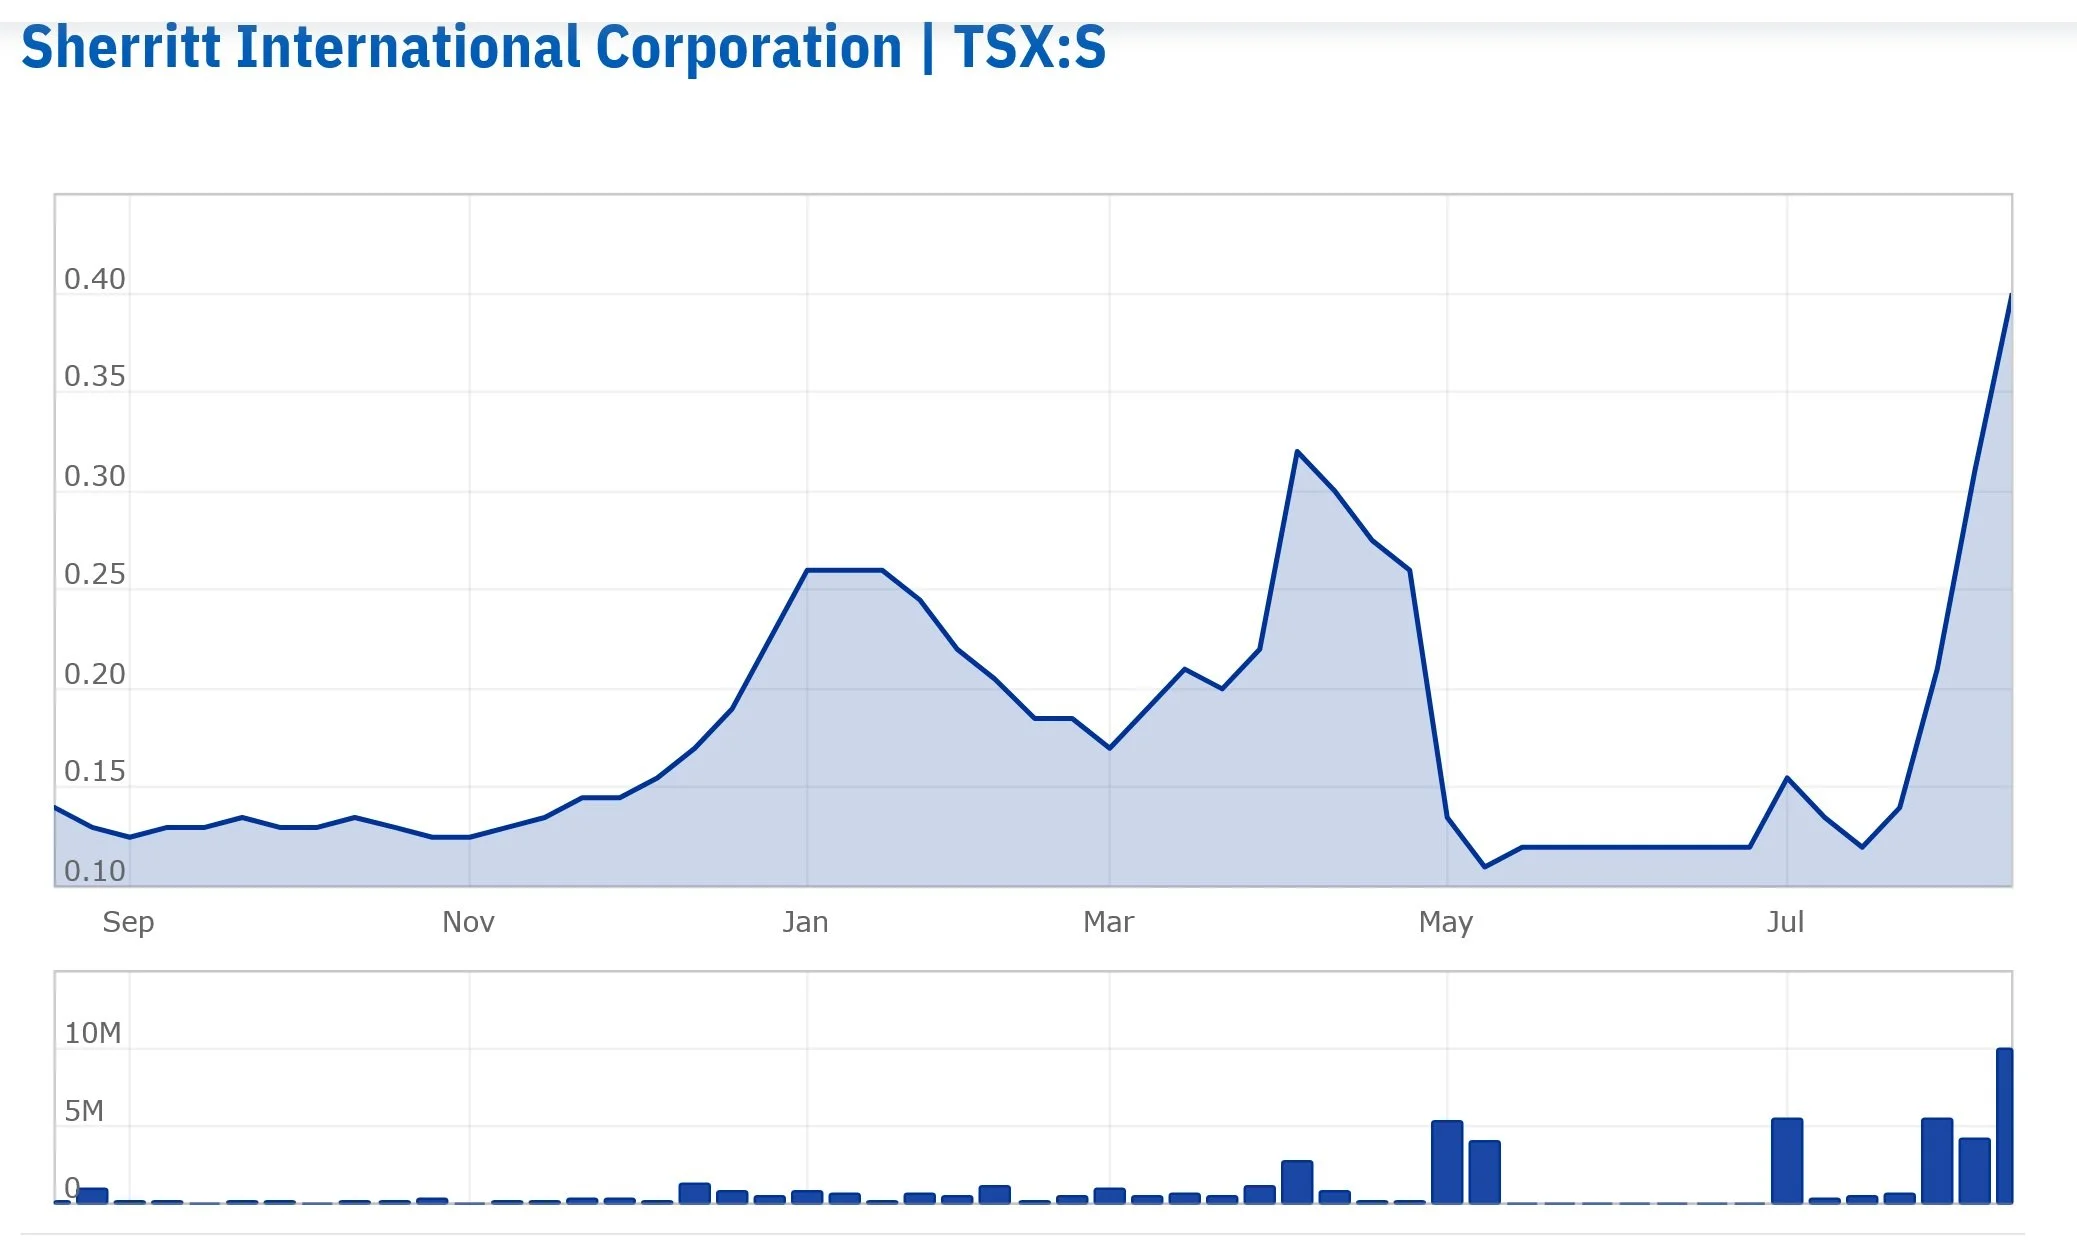
The alternative transaction term sheet provides: immediate equity capital at C$0.12 per share, without a discount to market; the right for eligible existing shareholders to participate at the same price as the sponsoring investors; committed equity funding without a third-party debt financing condition; participation by strategic and financial investors, including a reputable global metals and mining company with substantial operating, technical, refining, marketing and critical minerals expertise directly relevant to Sherritt's business; a strategic plan to strengthen Sherritt's North American nickel and cobalt platform; and written confirmation from the U.S. Department of State that it does not object to negotiations regarding the transaction.
Stakeholders should understand the stark difference between this alternative and the transaction currently being pursued by the Company.
The alternative transaction delivers immediate, market-priced capital and brings real operating capability directly relevant to Sherritt's business. It is backed by participants with experience in mining, metals, commodity markets, critical minerals and global industrial operations — expertise that matters when the Company faces urgent liquidity constraints, restart requirements and strategic decisions regarding the future of its nickel and cobalt platform.
It also gives existing shareholders the opportunity to invest alongside the new money on the same economic terms. By contrast, the Company's publicly disclosed transaction with Gillon Capital is based on a non-binding warrant structure, not an immediate capital injection. That warrant would give Gillon Capital the right to acquire control at a later date, would be exercisable for up to nine months, and is expected to be priced at a discount to the Company's share price, resulting in substantial dilution to existing shareholders upon exercise. No comparable operating or strategic partner has been publicly identified.
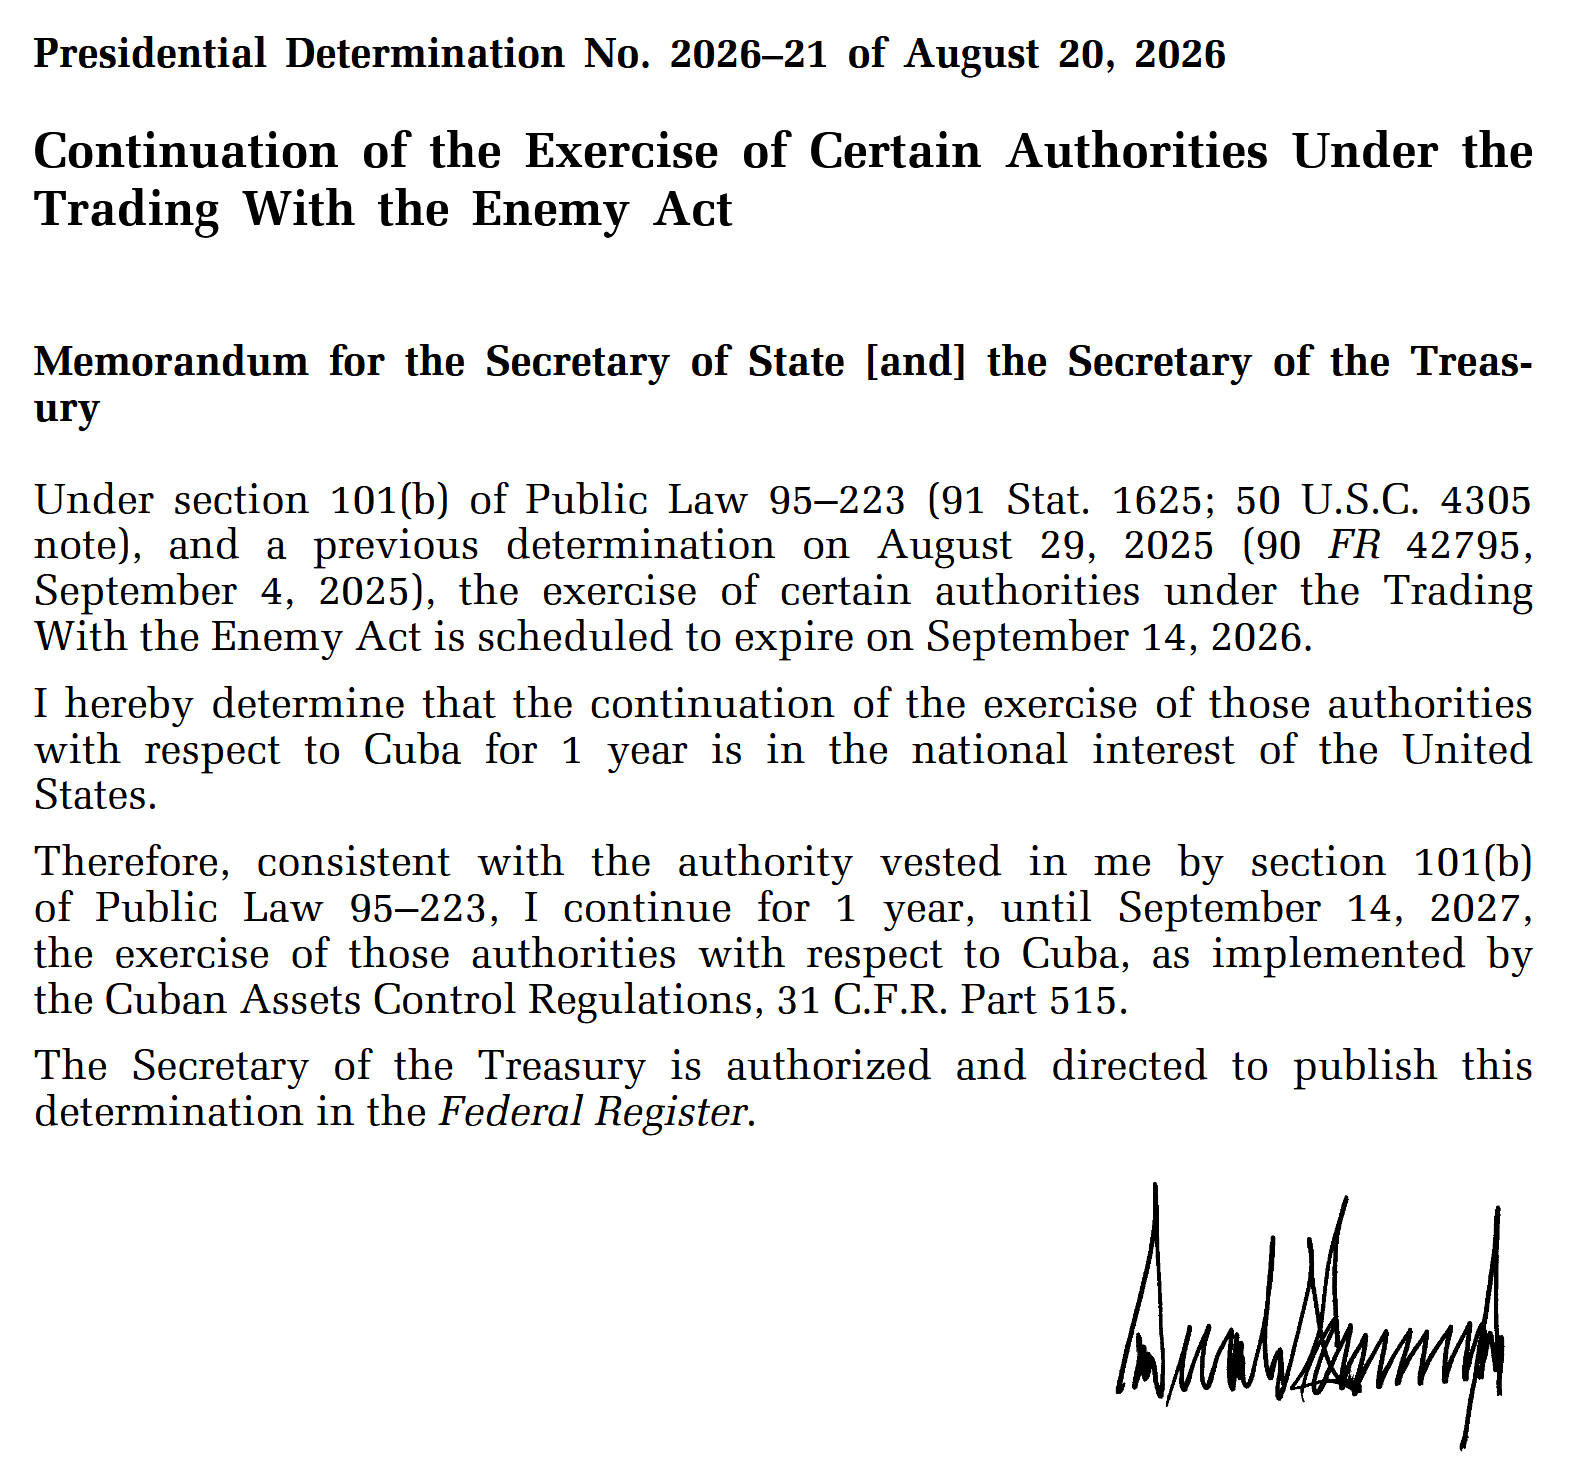
Both transaction paths have received similar feedback from the U.S. Department of State. The Company has disclosed that the U.S. Department of State and Department of the Treasury do not object to Gillon Capital engaging in negotiations with the Company. The alternative transaction is likewise supported by written correspondence from the U.S. Department of State confirming that the U.S. Department of State and Department of the Treasury do not object to the sponsoring consortium engaging in negotiations with Sherritt.
Stakeholders should not be led to believe that regulatory engagement or governmental support is unique to the Gillon transaction.
Nor does such engagement justify prioritising a discounted, conditional warrant structure over an available recapitalisation alternative that provides immediate capital, shareholder participation rights and relevant operating expertise.
The Board's obligation is not to protect a preferred transaction counterparty or transaction path. It is to evaluate all credible alternatives on the basis of value, financing certainty, shareholder treatment, operating capability, strategic merit, execution risk and overall stakeholder outcomes. It must also engage meaningfully with the stakeholders whose support may ultimately be required to implement any such transaction.
Given Sherritt's disclosed liquidity challenges, going-concern uncertainty and need for new capital, stakeholders deserve a fair process, balanced disclosure and a Board prepared to evaluate credible alternatives rather than continue down a single preferred path. Consistent with that objective, the Ad Hoc Group has provided the Company with an emergency financing term sheet intended to address near-term liquidity needs and preserve operational flexibility while a broader recapitalisation is pursued.
If the Company and its advisers continue to marginalise a credible recapitalisation alternative, limit meaningful engagement with the organised noteholder constituency, or pursue a process that impairs stakeholder value, the Ad Hoc Group is prepared to exercise all rights and remedies available to protect stakeholder interests, including with respect to the Company, the Board and, where appropriate, the Company's advisers.
The Ad Hoc Group remains prepared to engage immediately and constructively regarding financing and recapitalisation alternatives and reserves all rights with respect to the Company, its notes, the Board, the Company's advisers and any transaction requiring noteholder consent.
SOURCE Ad Hoc Group of the 9.25% 2031 Notes of Sherritt International Corporation”
Links To Related Analyses
Potential Triple Play? Carney, Diaz-Canel, Trump Deal. U.S. Secretary Of Defense Hegseth Wants Cobalt. Cuba Has It. Settling One Libertad Act Issue. And Opening Doors? August 23, 2025
Canada's Sherritt Questions "ability to continue" While OFAC Considers U.S. Company License Application To Save Company, Invest In Cuba, Settle A Certified Claim, Export Nickel And Cobalt To U.S. June 26, 2026
120-Day Cuba Countdown Clock. Will Trump Administration Approve U.S. Company's Takeover Of Canada's Sherritt International Corporation? June 23, 2026
Due To Trump Administration Cuba-Related Executive Orders And SDN List Additions, Canada's Sherritt International Corporation May Sell 55% To U.S. Company May 20, 2026
Canada's Sherritt Reports That "dissolution [of GNC] is required as a result of a material adverse change that is an immediate change under the MSA and that there is inadequate time for arbitration" May 15, 2026
Cuba Has Nickel And Cobalt. Vehicle Electric Batteries Use Nickel And Cobalt. Cuba Should Benefit. September 25, 2021